
Should I Pay Cash or Finance Equipment for My Business?
If you have the money in the bank, paying cash for equipment feels like the responsible thing to do. There is no debt, no interest, and no monthly payment hanging over you. Plenty of business owners take pride in it, and we understand why.
But having the cash to buy equipment and using that cash to buy equipment are two different decisions. So when you ask yourself whether to pay cash or finance equipment, the answer deserves more thought than it first appears. Before you write the check, it is worth asking five honest questions. In our experience, many business owners who ask them discover that **equipment financing** serves their business better. Others realize paying cash really is the right call. Either way, you will make a better decision.
1. What Else Could That Cash Do for Your Business?
Every dollar you spend on equipment is a dollar you cannot spend on something else. That could be payroll, inventory, marketing, a second location, or simply a healthy reserve for the unexpected. This is called opportunity cost, and it is the most overlooked part of the “pay cash or finance” question.
If keeping that cash available could help you take on more work, hire a key employee, or handle a slow season, then financing the equipment may be worth its cost. If the cash would otherwise sit idle with no better use, the math looks different.
2. Would You Still Have a Comfortable Cushion After Paying Cash?
A purchase that looks affordable today can feel very different three months from now when a customer pays late, a vehicle breaks down, or a slow stretch arrives. Many business owners like to know they could still cover several months of expenses after a big purchase.
Run the numbers honestly. If paying cash would leave you with less breathing room than you would like, spreading the cost over time through financing can be a way to protect your cash flow while still getting the equipment you need.
3. Will the Equipment Pay for Itself, and How Quickly?
Some equipment earns its keep almost immediately. A new machine that lets you take on more jobs, a truck that expands your delivery area, or a piece of equipment that cuts your production costs can generate income or savings that help cover the payments.
When the equipment produces revenue, financing lets the machine work for you while you pay for it, instead of making you wait until you have saved up the full price. Waiting has a cost too, in the jobs and customers you may miss in the meantime.
4. What Would Financing Really Cost?
This is where you should be careful, and where transparency matters most. The interest rate is only one piece. Ask about documentation fees, origination fees, filing fees, what happens at the end of the term, and how early payoff works. Some agreements include early payoff discounts. Others do not. The difference can add up.
Many of our past clients have told us that other brokers and finance companies never disclosed these details. That is why we spell out every fee and any early payoff discount structure before you commit. If a broker or lender will not give you the full cost in plain terms, that is a red flag.
5. Have You Talked to Your Tax Professional?
Tax treatment can affect the real cost of your decision. Many businesses may be able to deduct the cost of qualifying equipment, including financed equipment, under rules such as Section 179. Limits and eligibility requirements apply and can change from year to year, and your situation is unique.
We are not tax advisors, so we always recommend checking with your accountant or tax professional before you decide. It is a quick conversation that can save you from a costly surprise.
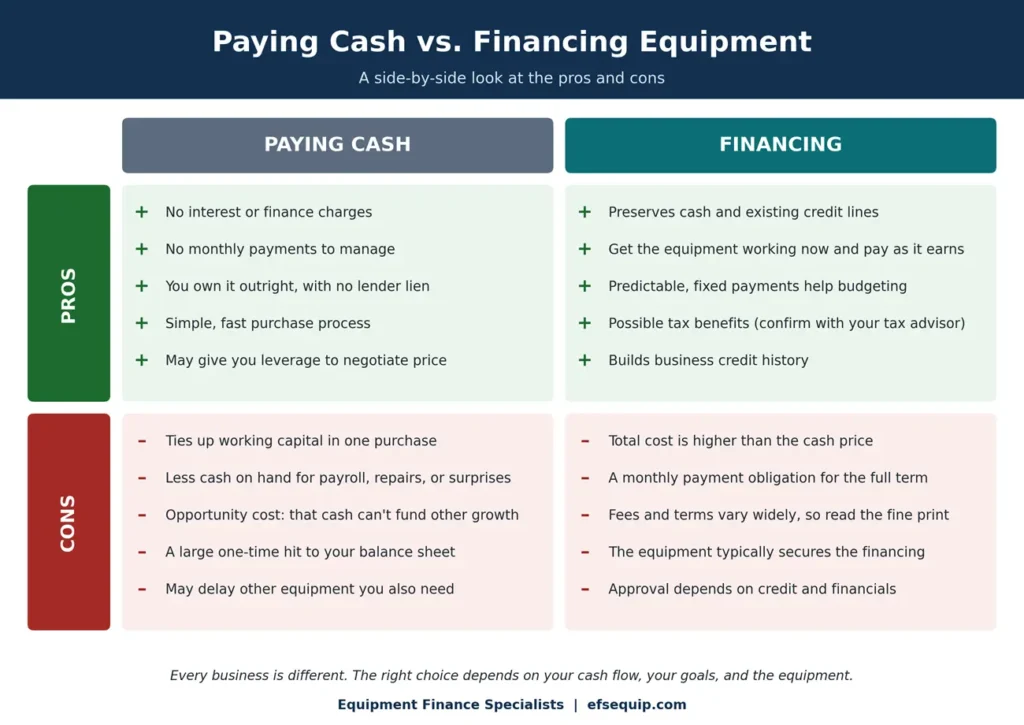
Pay Cash or Finance Equipment: Pros and Cons at a Glance
Here is a side-by-side summary of paying cash versus financing equipment:
When Paying Cash Is the Right Answer
Financing is not always the best decision, and we would rather tell you that than sell you a loan you do not need. Paying cash may be the smarter move if you have deep cash reserves, the purchase is small relative to your finances, you have no better use for the money, or the financing terms you qualify for are not competitive. If that is your situation, we will say so.
How EFS Helps You Decide
EFS is owned by an equipment finance specialist with more than 18+ years of experience in private financing with a nationwide network of over 100 private lenders. We are not tied to one lender, so we can look at your options and give you advice based on what is truly in your best interests.
We will walk you through the numbers, disclose every fee, and help you compare financing against paying cash. If financing is the better path, we will help you find the right lender. If cash is the better path, we will tell you that too.
Ready to Talk It Through?
If you are weighing your options on an equipment purchase, reach out to us for a straightforward conversation. You can click the green Call button below, or if you have already selected equipment and want to apply for financing, click here to fill out the prequalification form.
This article is for general information only and is not tax, legal, or accounting advice. Please consult your tax or financial professional about your specific situation.